Net Operating Income (NOI) Explained: The Key Metric That Makes or Breaks Commercial Deals
In this episode, Scott Dillingham walks through exactly how NOI is calculated, what a healthy DSCR ratio looks like, and how realtors can help clients structure deals that actually get financed. Net operating income is…
Show notes
If your client is buying a commercial property or business, the lender's decision will hinge on one number: Net Operating Income (NOI). In this episode, Scott Dillingham walks through exactly how NOI is calculated, what a healthy DSCR ratio looks like, and how realtors can help clients structure deals that actually get financed.
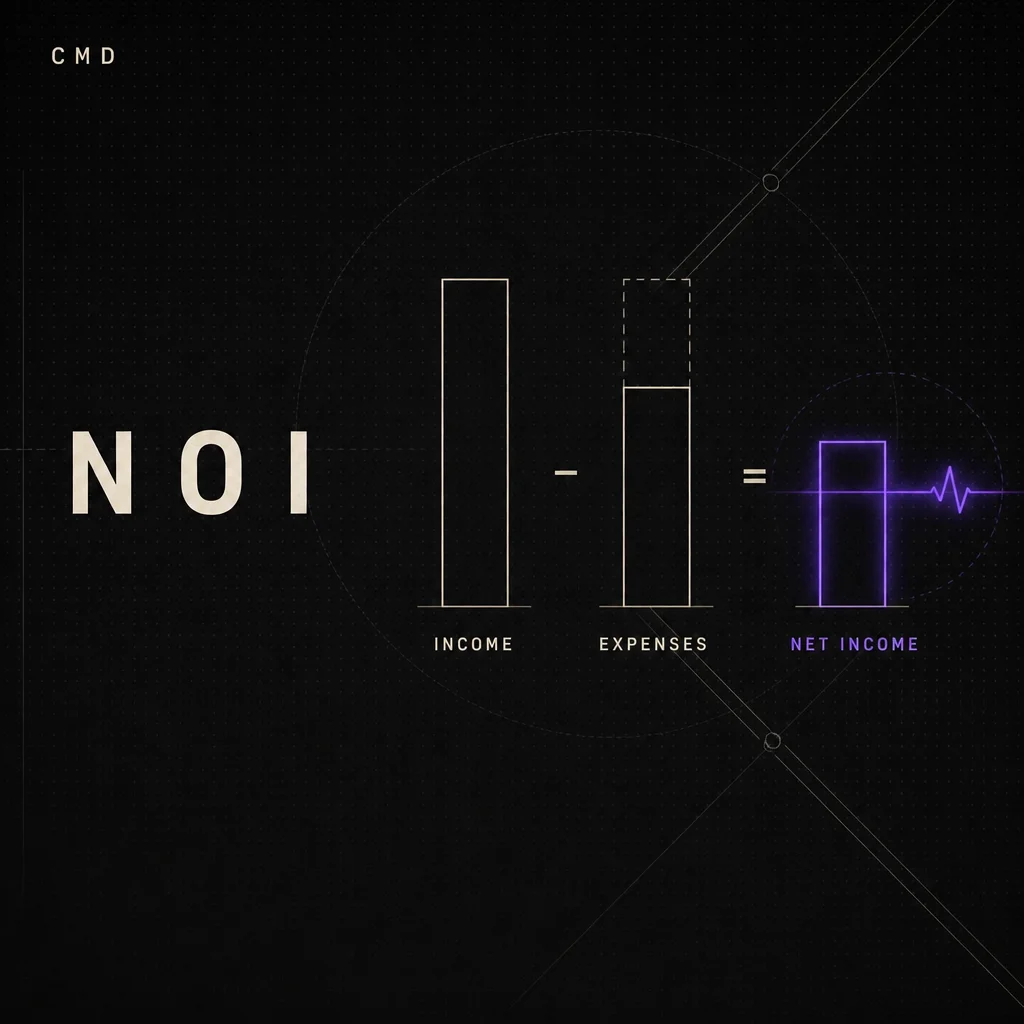
Net operating income is calculated by taking a property or business's total income and subtracting all operating expenses. This straightforward formula becomes the foundation for determining debt service coverage ratio (DSCR), which most commercial lenders require to be at least 1.2 or 20% surplus over expenses. Scott walks through exactly how lenders use this coverage ratio to calculate the maximum loan amount a borrower can qualify for when purchasing a business or commercial building.
One of the most valuable insights Scott shares involves how amortization periods dramatically impact loan sizing. Using a real client example involving a trucking facility purchase approaching four million dollars, Scott demonstrates how one bank offering only a 15-year amortization could not provide enough funding for the deal to work. However, another lender offering a 25-year amortization on the same property with the same DSCR requirement resulted in a significantly larger loan amount that made the acquisition possible. This real-world example highlights why comparing multiple lenders is essential for commercial transactions.
Scott emphasizes the importance of pre-qualifying deals before investing significant time in offers and showings. For realtors working with commercial buyers, having clients consult with a dedicated commercial lending team first can save countless hours and dramatically improve close rates. The LendCity commercial team offers complimentary phone consultations where they run NOI calculations in real-time, giving buyers immediate clarity on maximum loan amounts for specific properties or businesses.
Beyond the numbers, Scott addresses the emotional component of commercial purchases. Some buyers become attached to properties that simply do not make financial sense based on their NOI analysis. The debt coverage ratio requirement acts as a protective filter, preventing buyers from acquiring underperforming businesses or properties that could become financial burdens. This disciplined approach to commercial lending ultimately protects both the borrower and the lender.
For real estate professionals, understanding how commercial lenders evaluate deals provides a significant competitive advantage. By incorporating NOI analysis into your client consultation process, you position yourself as a knowledgeable advisor who helps clients make informed investment decisions rather than emotional purchases that may not qualify for financing.
Key Takeaways
- Net Operating Income Formula: NOI equals total income minus operating expenses, forming the foundation for commercial loan qualification and determining maximum borrowing capacity for business and property acquisitions.
- Debt Service Coverage Ratio Standard: Commercial lenders typically require a DSCR of 1.2, meaning the property or business income must exceed debt payments by at least 20% to ensure adequate cash flow coverage.
- Amortization Period Impact: Longer amortization periods significantly increase maximum loan amounts; a 25-year amortization can qualify borrowers for substantially larger loans than 15-year terms using identical DSCR requirements.
- Industry-Specific Lending Challenges: Certain sectors like trucking facilities and office space currently face tighter lending criteria with some banks scaling back programs, making broker relationships essential for finding willing lenders.
- Pre-Qualification Benefits for Realtors: Running NOI calculations before showing properties or submitting offers saves time, increases closing success rates, and prevents clients from pursuing deals that cannot be financed.
- 100% Financing Possibilities: Depending on loan size, location, business type, and overall income profile, some commercial deals may qualify for up to 100% financing through specialized programs.
- Emotional Decision Prevention: The debt coverage ratio requirement acts as a financial safeguard, preventing buyers from acquiring underperforming properties or businesses based on emotion rather than sound investment fundamentals.
Links to Show References
- LendCity Mortgages Commercial Team: lendcity.ca
- Commercial Loan Pre-Qualification Consultation: Contact LendCity for complimentary phone analysis
- Close More Deals Podcast: Subscribe for weekly real estate financing strategies
- (00:00) - - Introduction to Net Operating Income for Commercial Loans
- (00:30) - - NOI Formula Explained: Income Minus Expenses
- (00:45) - - Understanding Debt Service Coverage Ratio Requirements
- (01:01) - - Maximum Loan Calculation Using Coverage Ratio
- (01:31) - - Real Estate Investor NOI Applications
- (02:18) - - Client Case Study: Trucking Facility Financing Challenge
- (02:31) - - How Amortization Period Impacts Loan Size
- (03:19) - - Benefits of Working with Dedicated Commercial Teams
- (03:56) - - Free Phone Consultation Process Explained
- (04:04) - - Protecting Clients from Poor Investment Decisions
- (04:25) - - Closing Thoughts and Call to Action
Transcript
Introduction
Welcome to the Close More Deals podcast for realtors, the no BS podcast that turns stalled real estate deals into signed contracts and flaky buyers into loyal clients. I'm your host, Scott Dillingham, a battle-tested mortgage expert who's closed over $2B+ in real estate transactions. Each week, I unpack proven lending programs, negotiation hacks, mindset shifts, and insider tools from top producers so you can close faster, earn bigger, and crush your goals. Ready to dominate?
Hit play and let's seal the deal. Welcome back to the Close More Deals podcast. I'm your host, Scott Dillingham. Today, I'm going to be explaining net operating income and how it can help your client to get approved for their loan.
But not only that, it can help you avoid showing tenants or potential buyers properties that they're never going to qualify for. So what it is, a net operating income is the income subtract the expenses, right? That's the net operating income. So in Canada, we have a lot of people that want to buy businesses.
It happens in the States too, but specifically in Canada, the accountants do, it's a really nice like business financials. It shows the two-year summary back to back, like side by side, and you can see the net income. Well, how it works is we take that net income and we divide it into a mortgage payment. 2.
The Core Idea
So that means the income has to be 20% surplus over the expenses. And then we find out the max loan that the borrower can qualify for if they're buying a business or a max loan that their business could qualify for if they're buying a building. So when you're buying a building and you have an existing business, potentially you can finance up to 100% of this. It all does depend on the loan size, location, business type, and of course your overall income.
But we have helped many, many investors and business owners qualify under this. Now it's also used for real estate investors, right? So they'll look at the net operating income of a property to find the coverage ratio. And then that allows the lender to determine the potential value or size of the loan that they're willing to give the client.
So the net operating income is very important. Now the thing is, and why I keep recommending that if you guys have clients that they speak to a broker, preferably us, I would love that, but they speak to a broker because we just had a client who was purchasing a trucking facility and his bank was giving him a decent sized loan. It was almost 4 million. And they were only qualifying him over 15 years because that is their policy.
Right now, the trucking industry and office space is hard to finance. It's just the lenders have scaled back kind of what they want to do. And I think that's part of this bank's reasoning why they're at a 15 year amortization. So I know of another bank that's at 25 years.
Deep Dive
So we introduced them to them and the loan size is much bigger. It'll work. The size of the loan that the bank was giving, the deal didn't work. The borrower didn't have enough funds.
2, we're using the same net operating income per, you know, same client, same, same deal because the 25 year amortization, it drastically impacted the loan size. So this is something that you more than likely will not know, nor will your clients, right? When you just apply with one lender, that's why working with a dedicated commercial team is a fantastic way to guarantee and maximize your approvals. But what I like specifically, and I don't mind doing it, it does take a lot of time that kind of goes nowhere, but as if somebody is like buying a business or a property like this, we will quickly consult with you and the customer over the phone.
We'll run the numbers literally again over the phone. And we can tell you within a five minute phone call on the max loan for that property. And, you know, sometimes, you know, people get upset because they really wanted to, you know, they're letting their emotions get ahold of them and they wanted to, to buy this, this property, even though it's not a good one. So that's what this program stops.
It really stops you from buying crappy businesses, crappy properties. So it's fantastic. And for you as a realtor, if you have your clients go through this first, and we analyze the business financials first, then you're not spending all this time putting in offers and things like that. So it'll save you guys a lot of time, your success rate will go up.
Practical Steps
And obviously, you're going to close more deals. So I hope this helped. If it did, please like follow share all that good stuff. I really appreciate you guys.
And I'll see you next week.
Thank you so much for tuning into the show today. If you found value, please follow the show and rate it five stars, it would mean the world to me. And lastly, all the resources that we spoke about are at the bottom of the show notes.
Looking forward to seeing you in the next episode.